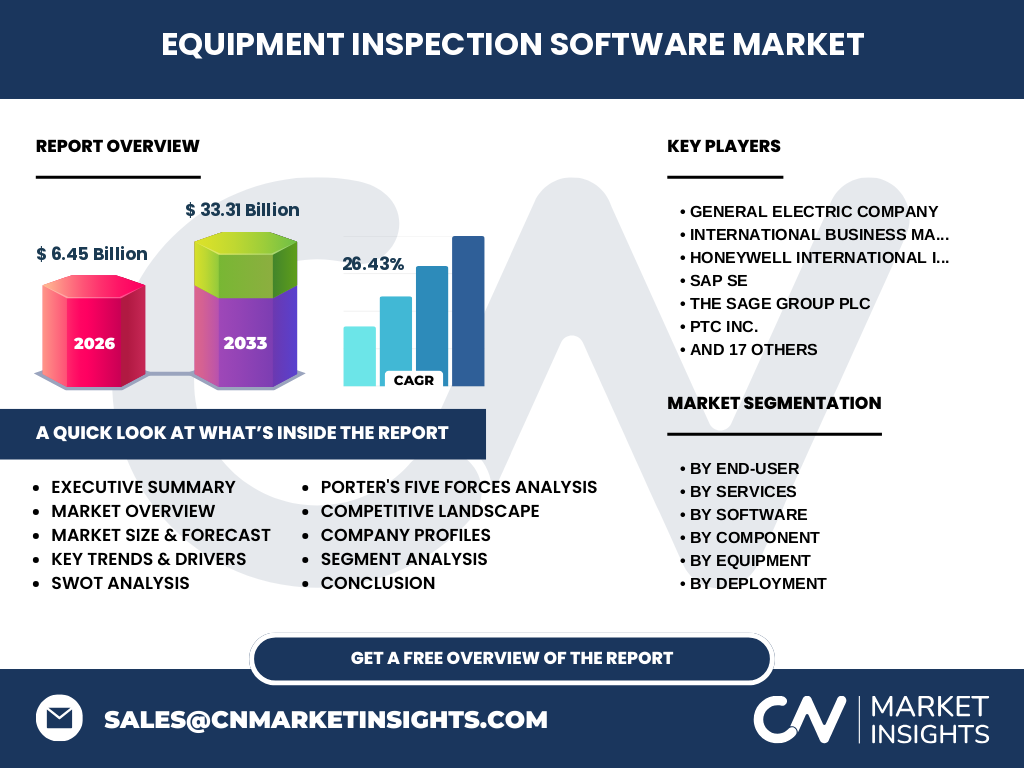
Market overview of the Equipment Inspection Software Market
The Equipment Inspection Software Market represents a critical digital layer in industrial asset lifecycle management. Valued at 6.45 Billion in 2026, this sector encompasses software designed to digitize safety, preventive maintenance, and functional audits. It is essential for operators managing complex industrial machinery and construction equipment, enabling real-time compliance with mandates from bodies like OSHA and ISO to minimize operational downtime.
Structural growth drivers and industry constraints
Primary growth is fueled by the imperative for operational efficiency in high-stakes environments. Key drivers include the urgent shift toward predictive maintenance and automated safety reporting. Conversely, legacy system interoperability remains a significant restraint, as firms struggle to integrate modern Visual Inspection Software with decades-old equipment sensors. Overcoming these integration silos is the industry's most pressing logistical challenge.
Emerging trends in the Equipment Inspection Software Market
The market is witnessing a profound shift toward AI-driven predictive analytics and mobile-first workflow automation. Companies like MaintainX Inc. and SafetyCulture Pty LTD are leading this trend by prioritizing intuitive user interfaces. These advancements allow field inspectors to capture high-fidelity visual data, facilitating instant synchronization with central Asset Performance Management systems, effectively reducing the latency between anomaly detection and corrective action.
COVID-19 impact and the recovery trajectory
The pandemic acted as a catalyst for digital transformation, forcing a rapid departure from paper-based inspection logs. While initial logistical hurdles disrupted implementation cycles, the recovery trajectory is robust. Organizations now prioritize remote audit capabilities and Cloud-Based deployment to ensure continuity. This period solidified the dependency on robust reporting and analytics software to maintain safety compliance despite fragmented on-site workforces.
Competitive benchmarking and strategic dynamics
Market concentration is high, featuring a mix of industrial titans and agile innovators. General Electric Company and IBM leverage their deep engineering heritage to provide comprehensive asset management suites. Meanwhile, specialized players like Tenna Inc. and Asset Panda Inc. capture niche segments through highly targeted fleet management tools, forcing legacy vendors to rethink their competitive strategies to fend off agile, cloud-native disruptors.
Executive summary of the Equipment Inspection Software Market
Our analysis indicates an explosive growth phase, with the market projected to reach 33.31 Billion by 2033 at a CAGR of 26.43%. The convergence of Predictive Maintenance and Workflow Automation is reshaping how equipment owners view maintenance—not as a cost center, but as a strategic advantage. Success in this market demands a sophisticated blend of software modularity and seamless API-led integration.
Forecast outlook for the 2027 to 2033 period
The Equipment Inspection Software Market is set for a massive expansion, scaling from current levels to a valuation of 33.31 Billion by 2033. This trajectory reflects a sustained compound annual growth rate of 26.43%. This growth is driven by the increasing complexity of Electrical Equipment and the global push for stricter safety and environmental compliance protocols across all industrial sectors.
Segmentation analysis by end-user and service types
Segments are divided between Inspectors and Inspecting Agencies, requiring high-compliance audit tools, and Equipment Owners, who prioritize predictive maintenance. Service segments like Implementation and Customization services have become critical as companies move beyond off-the-shelf software to bespoke deployments. This diversification allows vendors to capture value at every stage of the Equipment Inspection Software Market lifecycle, from initial training to ongoing maintenance upgrades.
Geographic distribution of the market
North America and Europe currently dominate the market, largely due to stringent regulatory requirements and high adoption rates of industrial machinery automation. However, the Asia-Pacific region shows the highest projected growth velocity. The localization of market constraints, such as differing electrical infrastructure standards, forces providers to adapt their platforms, favoring players that offer multi-language, multi-standard support across their software architectures.
In-depth regional performance review
In North America, the focus is on safety compliance, where firms like KPA Inc. excel in specialized safety management. Conversely, European markets prioritize sustainability and equipment lifespan. Emerging markets are rapidly adopting Cloud-Based inspection tools to bypass the infrastructure constraints of On-Premises setups. This regional differentiation is critical for market entry, as localized compliance and technical infrastructure dictate product feature priorities and implementation roadmaps.
Strategic positioning of leading companies
Leading companies like SAP SE and PTC Inc. position themselves as enterprise-wide digital backbone providers. In contrast, emerging leaders like Limble CMMS Inc. and Inspect Point Inc. compete through superior user experience and rapid deployment cycles. This bifurcation in strategy enables a robust ecosystem where both comprehensive suite providers and specialized application vendors can capture significant market share based on organizational scale and operational needs.
Porter's Five Forces assessment
The competitive landscape features high rivalry among established industrial software incumbents. While the threat of new entrants is mitigated by the need for deep technical expertise, the bargaining power of buyers is increasing as the market matures. The availability of open-source analytics and specialized modular software means that equipment owners can now demand higher interoperability, placing immense pressure on legacy providers to modernize their offerings.
SWOT analysis of the sector
Strengths: Massive digital efficiency gains and compliance automation. Weaknesses: High initial cost of Integration Services for legacy machinery. Opportunities: Expanding into Predictive Maintenance for renewable energy assets. Threats: Rising cybersecurity concerns regarding industrial IoT vulnerabilities. Our research indicates that the firms most likely to succeed are those balancing high-utility visual inspection tools with ironclad, enterprise-grade data security protocols.
Value chain analysis of the software industry
The industry structure flows from initial software engineering and data processing to deployment at the asset level. Value is generated primarily through data-driven insights provided to Equipment Owners. The value chain relies heavily on the quality of Integration Services, which bridge the gap between hardware sensors and cloud-based Reporting and Analytics Software, ensuring the data captured by inspectors is actionable for real-time operational decision-making.
Investment insights and high-potential areas
Investors should target companies that demonstrate modular architecture and high customer retention rates within the manufacturing and construction segments. The most high-potential area is the fusion of Visual Inspection Software with computer vision AI. Strategic acquisitions that consolidate Workflow Automation Tools with specialized predictive models present the best ROI opportunities as enterprises seek a single, unified source of truth for their Equipment Inspection Software Market requirements.
Conclusion and key takeaways for stakeholders
The Equipment Inspection Software Market is transitioning from a 'nice-to-have' digitizing tool into a mandatory industrial utility. With a projected growth to 33.31 Billion by 2033, the market rewards companies that prioritize scalability, API accessibility, and predictive analytics. Stakeholders must focus on the interplay between hardware-agnostic software and the growing demand for automated compliance, as these will define the leaders of the next decade.
Research methodology for market estimation
Our baseline estimates are triangulated through a synthesis of trade registry data, primary interviews with lead inspectors, and secondary macroeconomic indicators. We cross-reference vendor revenue reports with enterprise capital expenditure (CAPEX) trends in the construction and manufacturing sectors. This rigorous approach ensures our 6.45 Billion market size estimate is balanced against real-world deployment rates and historical software adoption velocity across major global ports and industrial hubs.
Scope of the report and coverage parameters
This report provides comprehensive coverage of the Equipment Inspection Software Market, analyzing the global landscape across six primary segments: Software, Services, Equipment Types, Inspection Methodologies, Deployment Modes, and End-Users. While focus is global, we specifically exclude minor, non-specialized general-purpose task management tools. Our analysis is framed by the 2027 to 2033 forecast period, providing a strategic view of technological maturation and market shifts.
Recent developments and strategic moves
Recent activity highlights a surge in M&A and strategic partnerships aimed at integrating AI. For example, Certainty Software Inc. and Snapfix Ltd. have recently announced feature enhancements focused on offline-first data synchronization. These product launches demonstrate a strategic move toward supporting remote, low-connectivity worksites. Meanwhile, the entry of major tech players into the Asset Performance Management space suggests a trend toward deeper integration between operational tech and standard inspection workflows.